What is the market overview, definition, scope, and industry significance of the Aluminum Billets Market?
Our analysis indicates that the Aluminum Billets Market represents a foundational segment of the global metallurgical sector, valued at $127.23 Billion in 2026. These semi-finished extruded products, manufactured primarily via Direct Chill Casting, serve as the critical feedstock for architectural profiles, automotive components, and electrical conductors. Industrial significance stems from their metallurgical versatility across Series 1000 through 7000 alloys, directly enabling lightweighting initiatives mandated by global environmental agencies across transportation networks.
What are the key market drivers, restraints, challenges, and opportunities shaping the Aluminum Billets Market?
Structural growth in lightweight vehicle manufacturing acts as a primary catalyst, whereas energy cost volatility and strict carbon border adjustment mechanisms imposed by the European Union serve as prominent restraints. Logistical bottlenecks in primary aluminum sourcing from smelters operated by companies like Rio Tinto and UC RUSAL create persistent raw material challenges. Conversely, surging demand for high-purity billets in renewable energy infrastructure presents lucrative expansion opportunities for forward-thinking extrusion enterprises.
Structural Growth Drivers in the Aluminum Billets Market
The transition toward electric mobility heavily accelerates adoption within the Aluminum Billets Market. Automakers increasingly rely on 6063 and 6061 alloy configurations for crash-management systems and battery enclosures. Furthermore, stringent urban building codes demanding energy-efficient thermal-break fenestration systems propel consumption in the building and construction sector, creating robust, sustained pull-through for both small-diameter and large-diameter extrusion billets.
How did the COVID-19 pandemic impact the Aluminum Billets Market and what does the recovery trajectory look like?
The pandemic triggered unprecedented supply chain fractures, forcing temporary smelter curtailments by major producers like Alcoa Corporation and Century Aluminum Company. However, post-crisis infrastructure stimulus packages and a rapid rebound in residential construction catalyzed a vigorous V-shaped recovery. Our research demonstrates that the Aluminum Billets Market surpassed pre-pandemic output levels by late 2022, underpinned by aggressive green-building mandates and localized supply chain reshoring.
Competitive benchmarking and strategic dynamics in the Aluminum Billets Market
Market concentration remains moderately fragmented among global titans and regional specialists. Industry leaders such as Norsk Hydro ASA, Novelis Inc., and China Hongqiao Group Limited dominate through vertically integrated operations spanning bauxite mining to downstream value-added extrusion. Strategic differentiation increasingly hinges on low-carbon primary metal sourcing, proprietary homogenization techniques, and localized scrap recycling loops designed to mitigate Scope 3 emissions.
Executive Summary of the Aluminum Billets Market
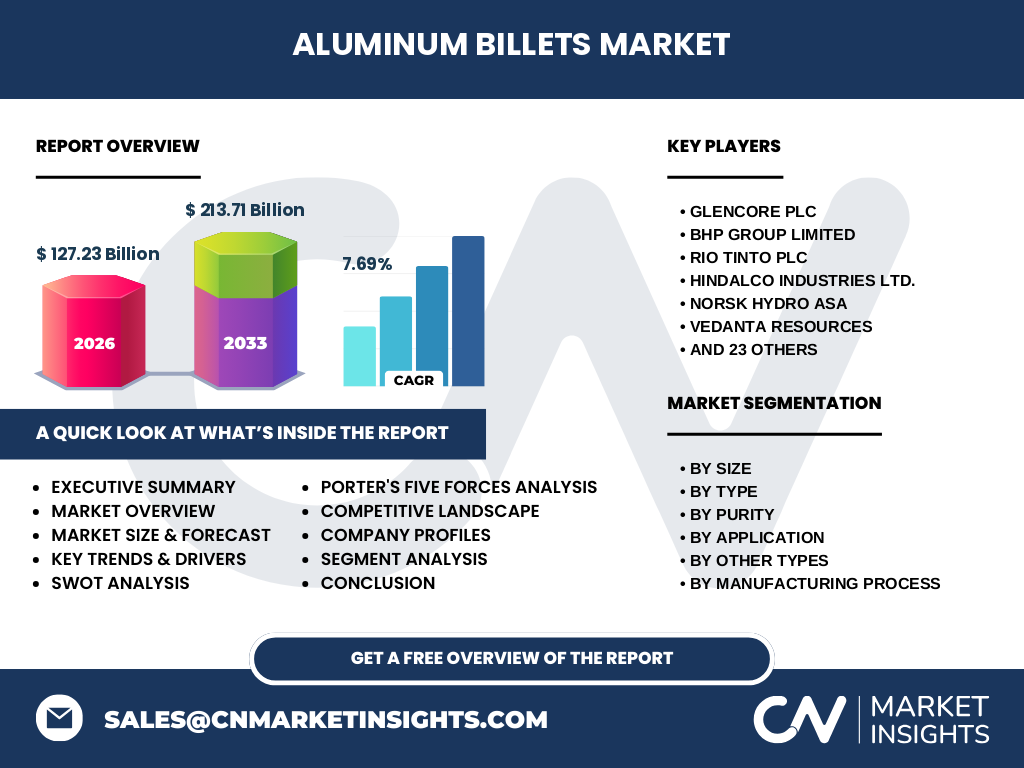
Our comprehensive executive synthesis reveals a thriving ecosystem projected to expand from $127.23 Billion in 2026 to $213.71 Billion by 2033, representing a robust CAGR of 7.69%. Growth is fundamentally anchored in lightweighting megatrends across automotive and construction verticals. Companies proactively investing in low-carbon smelting and advanced alloy development, such as Emirates Global Aluminium and Hindalco Industries, are best positioned to capture expanding market share.
Market forecast and projected growth for the Aluminum Billets Market from 2027 to 2033
The data suggests the Aluminum Billets Market will achieve remarkable acceleration, surging from $127.23 Billion in 2026 to reach $213.71 Billion by 2033 at a compound annual growth rate of 7.69%. This expansion is propelled by rising urbanization across developing economies and the aggressive electrification of global transport grids, necessitating high-performance metallurgical inputs tailored for complex extrusion profiles.
Segmentation analysis of the Aluminum Billets Market
Segmentation within the Aluminum Billets Market is categorized by size, type, purity, application, and manufacturing process. Size segments comprise Small-Diameter Billets and Large-Diameter Billets. Alloy types feature Series 1000 (1050, 1100), Series 3000 (3003, 3105, 3004), Series 6000 (6061, 6063, 6082), Series 5000, Series 7000, and Specialty Billets. Purity spans High Purity and Standard Purity, processed via Continuous, Direct Chill, or Semi-Continuous casting for Automotive, Construction, Electrical, and Transportation end-uses.
Regional market analysis and geographic distribution of the Aluminum Billets Market
Geographic performance exhibits distinct regional characteristics driven by localized industrial policies and smelting capacities. Asia-Pacific commands the lion's share of consumption and production, anchored by industrial hubs in China and India. Meanwhile, North America and Europe focus heavily on premium recycled content and stringent quality certifications for aerospace and automotive applications, governed by regulatory bodies such as the European Aluminium Association.
In-depth regional review of the Aluminum Billets Market
Asia-Pacific dominates the global landscape, fueled by massive infrastructure outlays and automotive manufacturing clusters in China, where giants like Aluminum Corporation of China (CHINALCO) operate extensive smelting networks. Conversely, the Middle East, anchored by Emirates Global Aluminium (EGA) and Aluminum Bahrain (Alba), leverages abundant energy resources to export high-quality primary billets to European and North American extrusion hubs through strategic maritime corridors.
Strategic positioning of leading companies in the Aluminum Billets Market
Market leaders employ distinct positioning strategies to maintain competitive moats. Rio Tinto Plc and BHP Group Limited leverage upstream resource ownership to secure raw material supply. Downstream specialists like Constellium SE and Kaiser Aluminum Corporation focus on customized, high-tolerance alloy development for aerospace and automotive clients, while recycling pioneers like Matalco Inc. capitalize on circular economy mandates by converting scrap into high-grade extrusion feedstock.
Porter's Five Forces analysis of the Aluminum Billets Market
The threat of new entrants remains moderate to low due to high capital expenditure requirements for greenfield smelting facilities and stringent environmental compliance. Bargaining power of suppliers is significant, heavily influenced by global alumina and bauxite pricing set by entities like Glencore plc and Vedanta Resources. Buyer power is counterbalanced by the specialized metallurgical specifications required for advanced automotive extrusions, limiting commoditization.
SWOT analysis of the Aluminum Billets Market
Strengths include the infinite recyclability of aluminum and its exceptional strength-to-weight ratio. Weaknesses involve high energy intensity during primary production. Opportunities abound in electric vehicle structural components and renewable energy framing. Threats center on macroeconomic recessions, trade tariffs on primary metal imports, and substitution threats from advanced carbon-fiber composites in niche aerospace applications.
Value chain analysis of the Aluminum Billets Market
The value chain initiates with bauxite mining and alumina refining, progressing to primary aluminum smelting or secondary scrap collection. Molten metal is subsequently alloyed and cast into billets via Direct Chill or Continuous Casting methods. These billets are distributed to extrusion plants operated by firms like Arconic Inc. and Shandong Nanshan Aluminum, where final profiles are shaped for end-users in automotive, construction, and electrical industries.
Investment insights and strategic recommendations for the Aluminum Billets Market
Investors should direct capital toward facilities integrating closed-loop recycling systems and low-carbon smelting technologies utilizing hydroelectric or solar power. High-potential areas include dedicated production lines for Series 6000 and 7000 billets tailored for electric vehicle battery trays. Acquisitions of regional recycling scrap yards by major players represent high-ROI plays to hedge against primary metal price fluctuations.
Conclusion and key takeaways for stakeholders in the Aluminum Billets Market
With the Aluminum Billets Market projected to surge from $127.23 Billion in 2026 to $213.71 Billion by 2033 at a 7.69% CAGR, the sector offers compelling growth. Success requires strategic alignment with decarbonization mandates, investment in advanced Direct Chill casting infrastructure, and rigorous supply chain diversification across key regional hubs in Asia, the Middle East, and North America.
Research methodology used to analyze the Aluminum Billets Market
Our proprietary baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with C-level executives at firms like Aluar and Vista Metals, and secondary macroeconomic indicators. We cross-reference production outputs from smelters worldwide with consumption data from automotive and construction associations to ensure uncompromised accuracy and market intelligence integrity.
Scope of the report covering the Aluminum Billets Market
This research report encompasses a comprehensive evaluation of the global Aluminum Billets Market across specified size, type, purity, application, and manufacturing process segments. Geographic coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Limitations include exclusion of downstream finished extruded profiles beyond primary billet conversion, focusing strictly on the semi-finished billet lifecycle.
Recent developments, company announcements, and strategic moves in the Aluminum Billets Market
Recent industry momentum is defined by green investments and cross-border partnerships. Notable moves include major capacity expansions by companies like Alcoa Corporation and Novelis Inc. focused on post-consumer scrap recycling integration. Furthermore, strategic joint ventures across Middle Eastern and Asian producers aim to secure stable alumina supply chains amidst shifting geopolitical trade tariffs and tightening carbon emission regulations.